On this page
Separate unusual from riskyFind the real complication firstThe property still has to make senseThen look at the leverageThe borrower matters tooThe exit has to survive contactDifficult files need fewerStructure can solve some problemsSometimes the correct answer isWhat lenders are really trying toWhat to rememberSome loans are easy to explain: stabilized property, experienced borrower, straightforward documentation, conservative leverage and an obvious source of repayment. Everyone understands the transaction before the coffee gets cold.
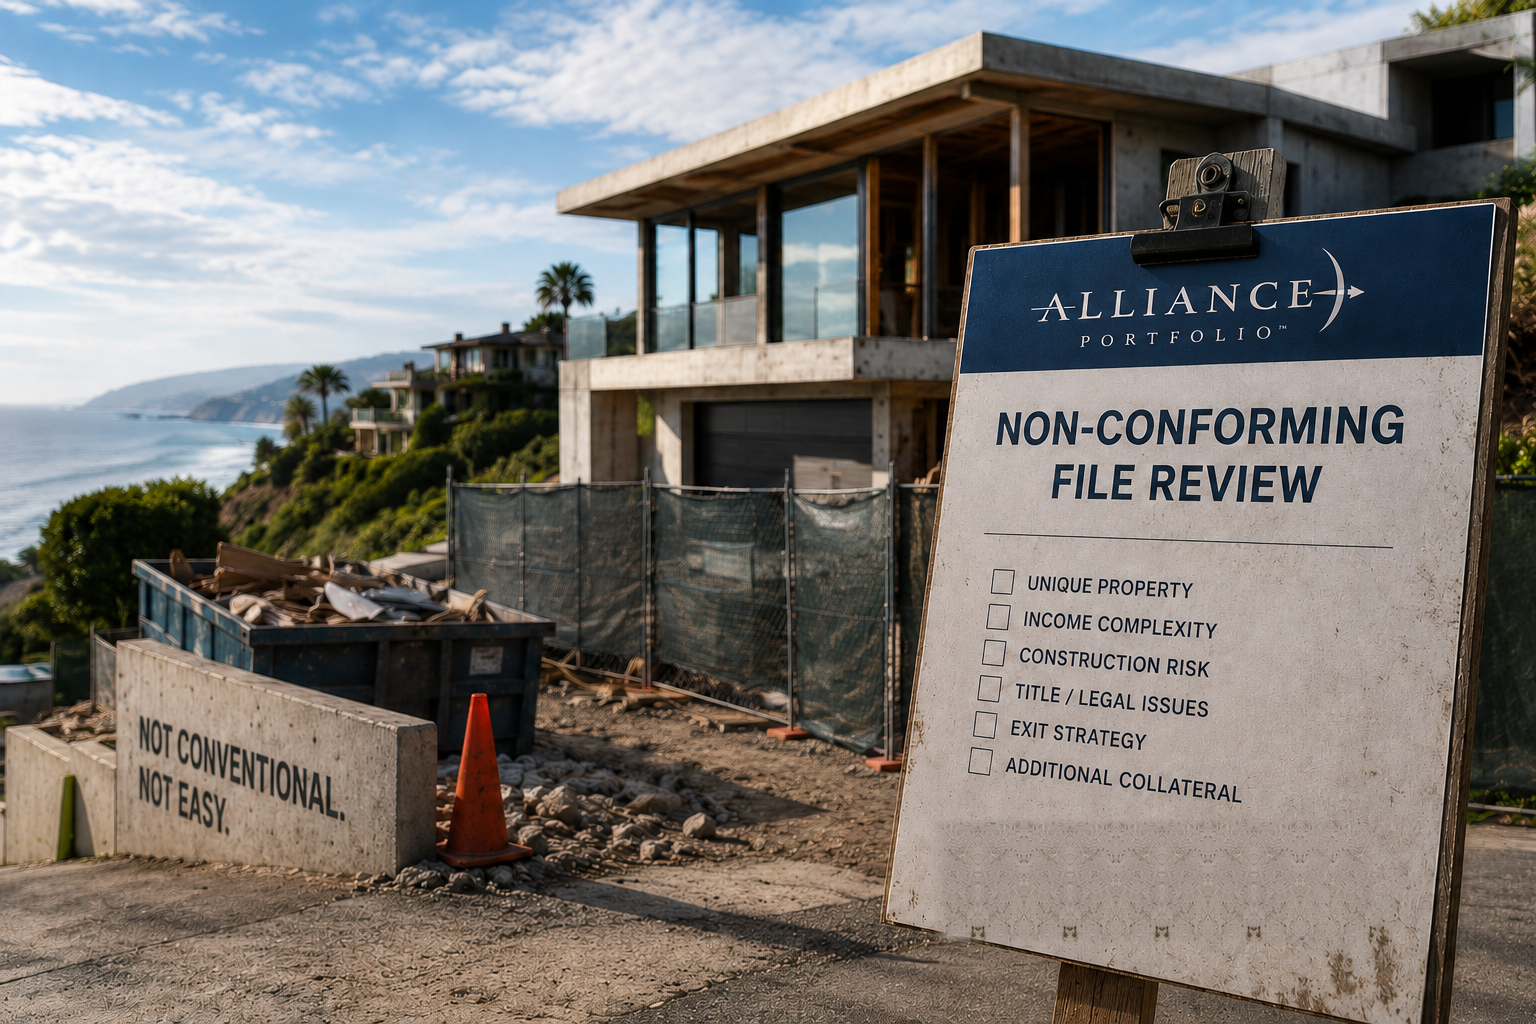
Then there are the other files. The property may be mid-renovation, the borrower may have strong assets but unusual income, conventional financing may be expected but not available yet, an attractive first mortgage may need to stay in place, or the closing date may be uncomfortably close.
That does not necessarily make the loan bad. It makes the underwriting more interesting.
Separate unusual from risky
Traditional lending systems work well when borrowers and properties fit the criteria those systems were designed around. Private lending can be useful when the transaction does not fit neatly, but flexibility should not be confused with ignoring risk.
A difficult file usually has something that requires more explanation. The lender's job is to determine whether that complication actually threatens repayment or simply makes the transaction harder to fit into a standardized process. Those are very different problems.
Find the real complication first
A borrower may say, "The bank won't do the loan." Useful information, but not much of an explanation. Why will the bank not do it? The property may not be stabilized, the closing may be too fast, construction may be underway, operating history may be short, ownership may have changed recently, documentation may be unusual, or a credit event may look worse without context.
Each problem points underwriting in a different direction. Until the lender understands why the file is difficult, it is hard to know whether private financing actually solves anything.
Sometimes the complication turns out to be manageable. Sometimes it turns out to be the warning label.
The property still has to make sense
A flexible lender may be willing to consider an unusual borrower or transaction structure, but real estate-secured lending still begins with the real estate. What is the property worth today? What supports that value? How marketable is it? Is the current condition materially different from the condition assumed in the valuation?
If the business plan does not work, what would the property realistically be worth under a different outcome? A beautiful appraisal does not improve a bad assumption.
If a property's value depends on another $2 million of construction being completed, underwriting the completed value without understanding who is funding that construction would be a fairly creative interpretation of current collateral.
Then look at the leverage
A difficult file becomes much easier to consider when there is meaningful borrower equity beneath the loan. LTV, existing debt and lien position start working together here.
A $750,000 second mortgage on a $5 million property may initially sound aggressive because the loan is junior. If the first mortgage is only $1 million, the combined leverage tells a very different story than the same second sitting behind $3.8 million of senior debt.
"Second mortgage" describes position. It does not finish the underwriting.
The borrower matters too
Private lending is sometimes described as purely asset-based. That can create the impression that the borrower barely matters as long as the property value is sufficient.
That is too simple. The borrower is the person expected to execute the plan and repay the loan. Financial resources, experience, liquidity and willingness to deal with problems matter, particularly when the transaction itself is complicated.
A lender may be more flexible about one weakness when other parts of the transaction are strong. Flexibility works best when everyone understands exactly what is being compensated for.
The exit has to survive contact with reality
Difficult private loans are often temporary by design, which makes the exit especially important. "Refinance" sounds reassuring until someone asks why the borrower cannot refinance today.
What has to change? Does construction need to finish, occupancy improve, a credit issue season, or another asset sell? A credible exit explains both what repays the loan and what has to happen before repayment becomes possible.
It should also survive delay. Rates move, buyers disappear, permits take longer, and construction schedules have been known to display a casual relationship with calendars.
A good exit does not have to be guaranteed. It does have to be believable.
Difficult files need fewer assumptions, not more
There is a temptation with unusual transactions to explain every weakness by adding another assumption. The property will be worth more after construction, rates will probably fall, the tenant should renew, the sale should happen quickly and costs should stay on budget. Soon the loan works beautifully, provided reality follows the PowerPoint.
A better approach identifies which assumptions the transaction truly depends on and stresses them. What if the sale takes longer? What if value is 10% lower? What if permanent financing costs more? What if construction costs rise? The more difficult the file, the less room there is for magical thinking.
Structure can solve some problems
Sometimes the answer is not simply yes or no. The loan amount can be reduced, additional collateral may be available, a different lien position may make more sense, the term can better match the expected exit, or conditions can be satisfied before funding.
That is one benefit of transaction-specific underwriting. A lender may be able to structure around a clearly identified issue rather than reject the entire transaction because one characteristic falls outside a predetermined box.
But structure should solve a real problem. Adding complexity because the original transaction does not make economic sense is not structuring. It is decorating.
Sometimes the correct answer is still no
A difficult file is not automatically a bad file. Unfortunately, some of them are.
The property value may not support the request, borrower equity may be too thin, senior debt may leave no reasonable recovery cushion, or the exit may require several optimistic events to happen in sequence. Private lending provides flexibility. It does not repeal arithmetic. A thoughtful no can be more valuable than weeks spent chasing a yes that was never realistic.
What lenders are really trying to answer
Most difficult-file underwriting eventually comes back to a small group of questions: What is the property realistically worth today? How much total debt will sit against it? How much borrower equity is at risk? Who gets paid before this lender? Why does conventional financing not work right now? What has to happen before repayment becomes possible? What happens if the exit takes longer or costs more?
If those answers hold together, the fact that a transaction is unusual may matter less than it first appeared. If they do not, simplifying the paperwork will not save it.
Collateral
What is the property realistically worth today, and what supports that value?
Leverage
How much total debt will sit against it, and in what positions?
Borrower
How much equity is at risk, and can this borrower execute the plan?
Exit
Why is conventional financing unavailable now, and what has to change?
Downside
What happens if the exit takes longer or costs more?